Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
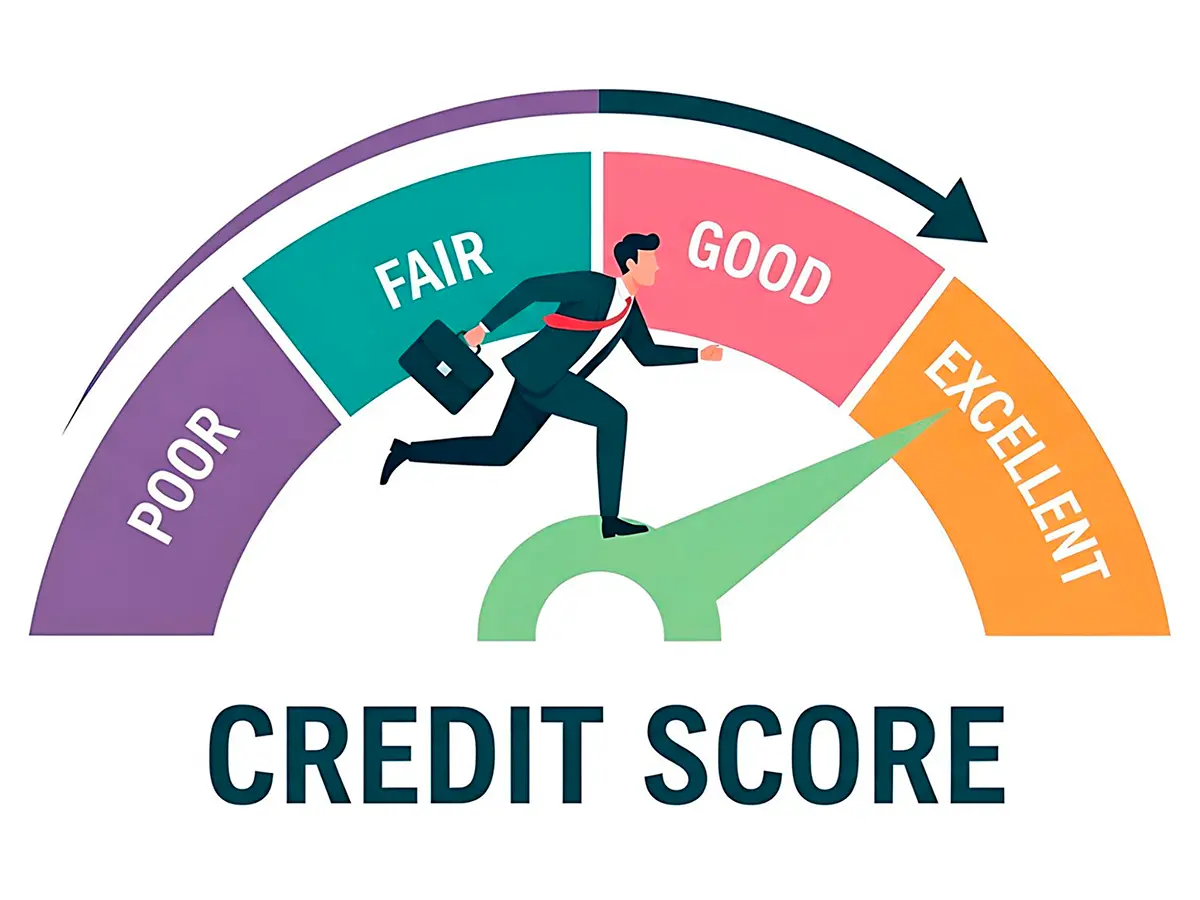
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair baytown texas guide to clarity and control
Start from a clean snapshot
Your path begins with visibility. Pull your free credit reports from all three bureaus and read them line by line. Circle late payments, collections, duplicate accounts, and personal information that doesn't look like you. Keep notes. You are building a map, not guessing in the dark.
- Save PDFs and take screenshots so dates and balances are preserved.
- Match every negative item to a statement, receipt, or message thread.
- Sort issues into: clear errors, questionable items, and accurate negatives.
Dispute with precision, not volume
Errors happen - wrong balances, accounts that belong to someone else, paid debts still marked unpaid. Dispute those with facts. Provide documents and a calm explanation. Bureaus generally have 30 days to investigate once they receive your dispute.
- Gather proof: payment confirmations, letters, police reports if identity theft is involved.
- Write a short dispute describing the inaccuracy, the correct information, and your evidence.
- Send to the bureau and, when useful, to the furnisher (the bank, lender, or collector).
- Track responses and due dates on a simple calendar.
Gentle limitation: you can't force the removal of accurate, timely negatives. The goal is accuracy and context, not erasing history.
Build fresh positives in Baytown
While disputes move, add good data. Consider a secured card from a local Baytown credit union, a small installment builder loan, or becoming an authorized user on a well-managed account. Keep limits modest and predictable.
- Use 5% - 10% of your limits and pay before the statement cuts.
- Set autopay for at least the minimum on payday.
- Avoid opening several accounts at once; pace matters.
Real moment: sitting at a table off Garth Road, you schedule two autopays and see your utilization drop below 10%. Quiet win, no fanfare.
Manage balances and timing
Utilization - the slice of credit you use compared to limits - moves scores fast. Under 30% is workable; under 10% is better. If a card reports high, make a mid-cycle payment. If a due date clashes with your Baytown shift schedule, ask the issuer to move it. Small adjustments compound.
If you seek help, choose carefully
Some professionals are useful, especially for identity theft or complex reporting issues. Still, stay alert.
- Be wary of guarantees or advice to create a new identity.
- Understand pricing, scope, and cancellation terms in writing.
- Measure results by verified corrections and healthier habits, not promises.
Protect the gains
Turn on credit monitoring and fraud alerts. Consider a security freeze to block new accounts until you lift it. During storm season, keep digital copies of disputes and mail receipts in cloud storage so deadlines aren't lost. Accurate negatives like late payments may remain up to seven years, and bankruptcy can last up to ten, but consistent on-time payments and low balances can outweigh old marks over time.
You don't need perfection to move forward. You need a system you'll actually use. Step by step, credit repair in Baytown becomes less about fear and more about steady control.
Top 10 Best Credit Repair in Baytown, TX - February 2025 - Yelp - Credit Glory Credit Repair, ASAP Credit Repair, Independent For Life Financial Services, ...
We can help you fix that. We are a baytown, Texas-based credit repair company that assists customers in getting the homes, loans, and financing they want. We ...
Established in 2008, ASAP Credit Repair Baytown is a family-run business specializing in credit repair. A hub for educating Americans about financial and credit ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.